Sixty Percent of the Wrong Number
Last spring I sat down to answer one question about my own household. If I could not work for a year, what would actually land in our account?
I run a financial planning firm with no one else in it. No partner to carry my clients. No group plan sitting behind me. Whatever protection my family has is whatever I decided to build.
It took less than twenty minutes to log in and confirm the numbers. The number held up, because I had done the work before. But the exercise stayed with me, because I kept thinking about how rarely anyone runs it, and how many capable people carry a percentage in their head they have never once confirmed.
The asset that never prints on a statement
The largest asset most working families own is not the retirement account. It is not the brokerage balance or the house. It is the paychecks still to come. In your peak earning years, the income still ahead of you dwarfs everything already saved. It is the engine. The accounts are only what the engine has produced so far.
That engine gets almost none of your attention, and the reason is simple. It does not move. There are two types of knowledge. One expires: quarterly earnings, the market's mood, the headline that owns your morning and means nothing by Friday. The other is permanent, and it struggles to hold your attention for the very reason that it holds still. Your portfolio balance is expiring knowledge. You check it, and it will read differently the next day. The terms protecting your income are permanent knowledge. They will govern your family for years, and most people earning well into six figures have never read them once.
What sixty percent actually covers
Ask a room of senior professionals whether they carry disability coverage and nearly every hand goes up. Ask what it pays and the room goes quiet. The answer, when it comes, is usually a figure from an orientation slide nobody has looked at since. The coverage is real. The understanding of it is not.
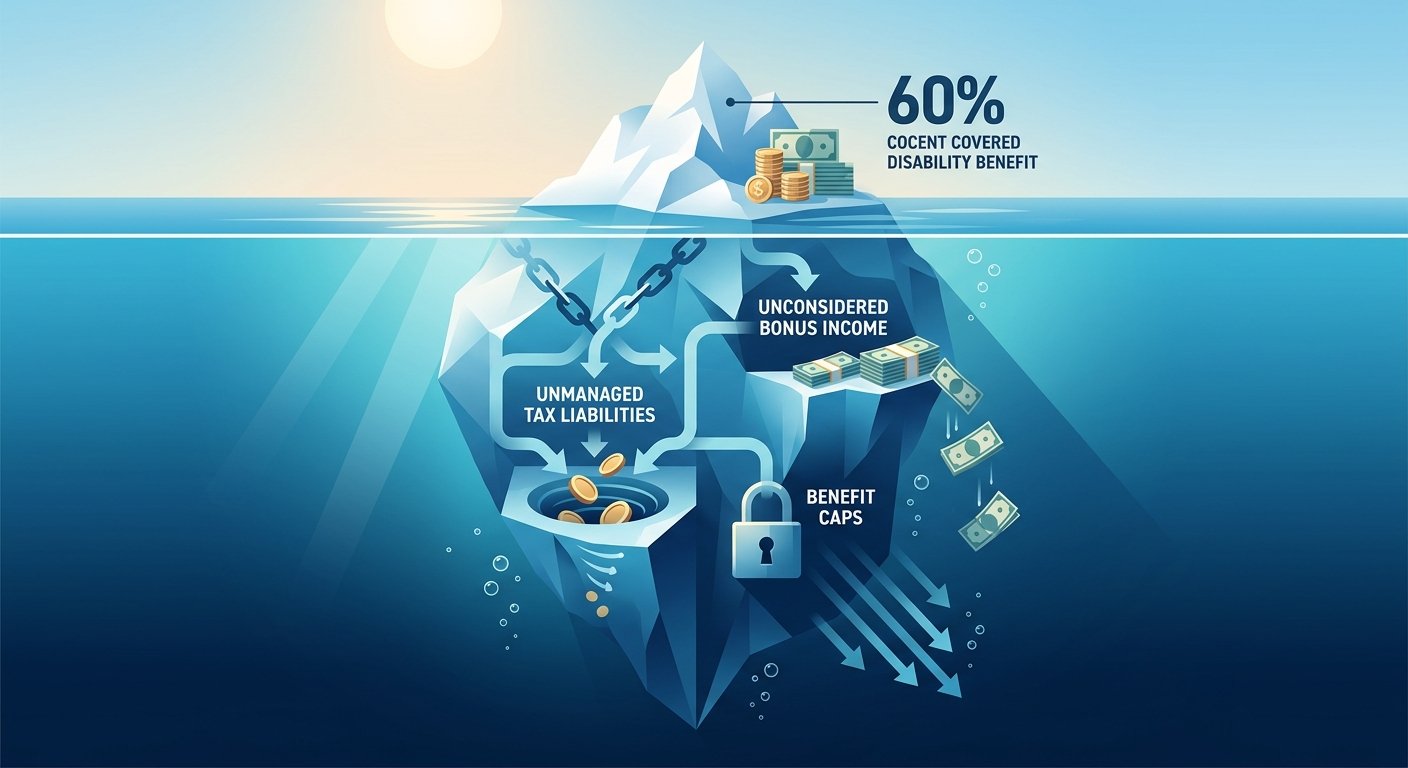
Here is the shape of most employer long-term disability plans, worth knowing in your own words rather than a benefits brochure. The plan replaces around sixty percent of your base salary. Not sixty percent of what you earn. Sixty percent of base. Your bonus sits outside it. Your equity sits outside it. Then a monthly cap sets a ceiling on the benefit, a number a base salary might never reach, but a full income clears without trying. And when your employer pays the premium, which is the common arrangement, the benefit that finally reaches you is taxed on the way in.
Picture a household where one spouse earns three hundred fifty thousand a year, with two hundred fifty of that in base pay and the rest in bonus and equity. The plan promises sixty percent, which sounds like a floor you could stand on. Sixty percent of base is one hundred fifty thousand. The monthly cap, though, tops out closer to one hundred twenty. And since the company paid the premium, that one hundred twenty arrives taxable, settling somewhere in the mid-eighties once withholding is done. The slide said sixty percent. The household is covered on roughly a quarter of the income it actually lives on. Nobody misled anyone. The gap was in the plan from the first day of enrollment, printed in a document that was never opened.
Two incomes, two blind spots
A dual-income household has a quiet advantage here and usually does not use it. If one paycheck stops, the other keeps the lights on, which is a real cushion a single-income family does not have. But two earners also means two separate group plans, two separate sets of fine print, and two defaults set at different companies on different days by a person too busy to read them. The coverage was never designed as a pair. It was assembled by accident.
I sit at the opposite end of that spectrum, and it taught me the same lesson from the other side. As a solo practitioner, I have no group plan to misread. There is no default to inherit and no cap to discover. My income protection is whatever I chose to build, which sounds freeing until you realize it puts the whole number on me.
When I ran my own exercise, I could not lean on a percentage from an orientation slide. I had to look at the actual figure and ask whether it carried Theresa and the kids for as long as it needed to. It was not a comfortable number to sit with. It rarely is. That is the same question a two-income household should be asking about each plan separately, and the honest answer never comes from memory. It comes from the document.
The one window where this can change
This is not something you adjust on a random afternoon. Group coverage moves during one window a year, when benefits open for election, and that window is why you should look now instead of someday. Most plans offer a way to buy up, to raise the replacement percentage or add a supplemental layer that reaches the income the base plan steps around. Many let you pay the premium yourself, which changes how the benefit would be taxed if it is ever paid out.
I am not telling you to buy anything. Whether a buy-up belongs in your plan depends on your whole picture, and that is a conversation rather than a paragraph. What I am telling you is that the option exists, that it usually costs little next to the income it is built to protect, and that it stays invisible until you go looking.
The habit underneath all of this is the one that line I noted earlier about knowledge. Ask how long you will care about the information in front of you. The market figure you refreshed at breakfast will not matter by the weekend. The coverage on your income matters for as long as your family depends on you earning it. One of those has a claim on your morning. For most of us, it is not the one we hand it to.
While enrollment is still open, pull your benefits summary and find three numbers.
The percentage of pay your long-term disability replaces.
The monthly cap on that benefit.
Whether the benefit is taxed.
Multiply the cap out to a full year and set it beside what your household actually spends. Do it for each earner in the house, not only the higher one.
If the two are close, you are finished, and you can close the file with a clear conscience. If they are far apart, you have just turned twenty quiet minutes into the most useful question you will bring to whoever helps you plan.