
WHO WE SERVE
TAMMA works with dual-income parents in Director-level and above roles whose financial lives have outgrown the time they have to manage them.
Both careers are demanding. The kids' schedules are full. And somewhere along the way, the money got complicated. Equity comp. A 401(k) at the old employer and another at the new one. Estate documents from before the kids were born. A tax return that surprises you every April.
None of it is broken. There's just no one holding all of it together. That's the job I do.
If any of this sounds familiar, you're who I built TAMMA for.
"We make good money, but I don't know where it all goes."
"We have a plan, but I'm not sure anyone is actually watching it."
"I'm tired of explaining our situation to three different people."
"My CPA does my taxes. My advisor does my investments. Who's seeing the whole picture?"
These aren't investment problems. They're coordination problems. And they don't get solved by adding a fourth professional to the list.
The Problem I Solve
Most families I meet already have financial professionals. An advisor somewhere. A CPA they see once a year. An attorney who drafted documents a decade ago. An insurance agent they can't quite name.
Here's what they don't have: anyone connecting those pieces. The advisor doesn't see the tax return. The CPA isn't aware of the equity comp. The estate documents don't reflect the family that exists today. Every professional is doing their job, and the whole is still less than the sum of the parts.
I built TAMMA to be the one relationship that replaces the three or four you'd otherwise have to manage. Planning, investments, insurance review, estate coordination, and taxes are held in one place by one person who knows your family.
And I mean taxes literally. I'm an Enrolled Agent, and I prepare and file returns for most of the families I work with. Not "I'll coordinate with your CPA." I do the work. When the person building your plan is the same person signing your return, tax planning stops being a once-a-year scramble and becomes part of how your financial life runs.
Is This You?
The families I work with usually look like this:
Both partners work in demanding senior roles at the Director level and above. Household income is typically $250,000 or more. There are kids at home, with everything that brings: activities, school decisions, and college on the horizon. The money questions have multiplied faster than the time available to answer them.
My minimum annual cost is $5,000. I share that here because your time matters, and so does mine. If that number works for your situation, the next step is a conversation.
What It Costs
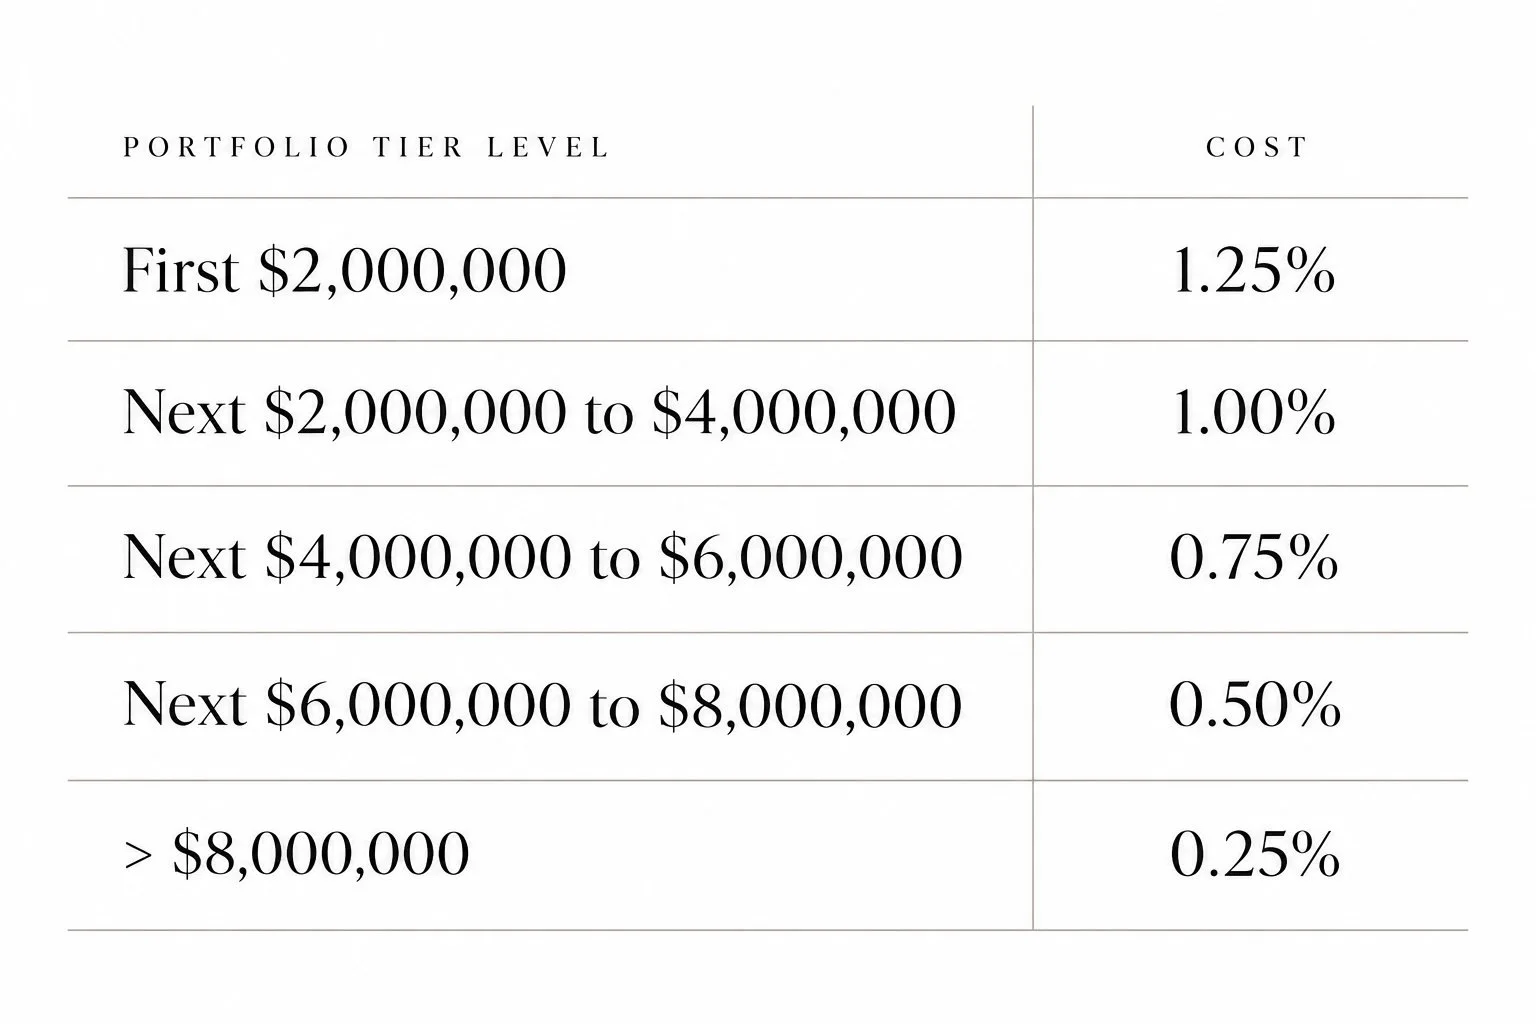
The cost is 1.25% annually on the portfolio I manage, billed quarterly, with rates that step down as your portfolio grows. Here's what that looks like across a year for a $1.2 million portfolio:
Q1: $1,200,000 → $3,750
Q2: $1,150,000 → $3,593.75
Q3: $1,240,000 → $3,875
Q4: $1,300,000 → $4,062.50
The cost is deducted from your portfolio each quarter. There's no invoice, no check to write, and nothing added to your monthly expenses. Once your portfolio passes $1 million, tax preparation is included in your cost: no separate CPA bill, no handoff. The same person who builds your plan prepares your return.
There is a minimum quarterly cost of $1,250 regardless of portfolio value.
The Next Step
I'm working with new families. The first conversation is an alignment meeting. We'll walk through where things stand, what's on your mind, and whether this is a fit on both sides. No charge, no pitch, and no expectation that you decide anything in the room.