Why the Account That Funds Itself Always Wins
There is a spreadsheet on my laptop I do not like to open. It has four columns, one for each of my kids. The triplets graduate high school in the spring of 2029. Mackenzie graduates the year after. For about twelve months starting in the fall of 2029, Theresa and I will have three tuition bills landing in the same window.
I am fifty. That same window is supposed to be my peak retirement-saving decade, the years every article tells you to put your foot on the gas and max everything out.
So which one wins? The retirement, or the college bills I can already see coming? For a long time we answered that question without ever actually deciding it. And the way we answered it is the same way most of the two-income households I work with answer it, quietly, by default, without anyone choosing.
The goal that funds itself
Here is what happened in my house. During my corporate career, the 401(k) came out of my paycheck automatically. It always got funded, because it funded itself. I never saw the money, never made a decision about it, and it went to work every two weeks without my involvement. That is exactly why it worked.
The 529s were different. They required Theresa or me to move money on purpose, every month, against everything else that same money could do. And on purpose, every month, is the one thing a family with two careers and four kids does not have the capacity for. So the college accounts got whatever was left. Some months that was a little. Some months it was nothing.
The families I sit with are not people who cannot save. These are director-level households with real income coming in, often with equity or a bonus arriving on top of the base. The problem is never the size of the paycheck. It is that one goal is automated, and the others are not, so the others quietly lose to the only goal that never required a decision. We were not choosing retirement over college. We let the account that funded itself win, every month, for years, and called it a plan.
Two forces that make it worse
Two things turn that quiet loss into a real gap.
The first is lifestyle creep. The raise arrives, the bonus arrives, and the surplus that was going to fund the reserve gets absorbed into the way you live before it ever becomes savings. Nobody is spending recklessly. Spending rises to meet income, the way it always does, and the goals that were supposed to get the new money get nothing new. For a dual-income family, this is easy to miss, because two rising incomes mean two rising lifestyles, and the surplus you picture on paper is smaller in the account than it looks in your head.
The second is the false comfort of two incomes. When both of you work, it feels like you have a built-in backup. If something happens to one job, there is still the other. That holds right up until the setback that does not wait. A role gets cut. A company reorganizes. A health issue takes one of you out of work for six months. Progress happens too slowly to notice; setbacks happen too fast to ignore. The buffer you were going to build next is the one you need now, and the second income you were counting on is the one that just disappeared.
Parallel paths, not a sequence
The reason we get this wrong is that it is easier to think in black and white than in probability. Max the 401(k) first. Then build the reserve. Then start on college. One thing at a time. It feels like discipline.
But every one of those goals has a live clock. Your kid does not wait to turn eighteen until you have finished maxing your retirement. The layoff does not wait until your emergency fund is full. Run these as a sequence and the goals at the back of the line never actually start. The math only looks clean on the whiteboard, where the clocks are turned off.
The alternative is to stop picking. Parallel paths mean every goal gets automated to a floor, not maxed one at a time. The retirement contribution gets funded to the match and a set amount beyond it, not every available dollar. The reserve gets its own automatic transfer on the same day the paycheck lands, ring-fenced so it is not the account you raid for a vacation. The college account gets its own recurring contribution, small if it has to be, but real.
A family with four thousand dollars of monthly surplus does not pour all four thousand into retirement and hope. It splits the surplus across all three goals, automated, on the same day, so no single goal depends on anyone remembering to feed it. In a two-career family, that also means deciding which paycheck funds which goal, so the coordination lives in the setup once instead of in a monthly conversation neither of you has time for.
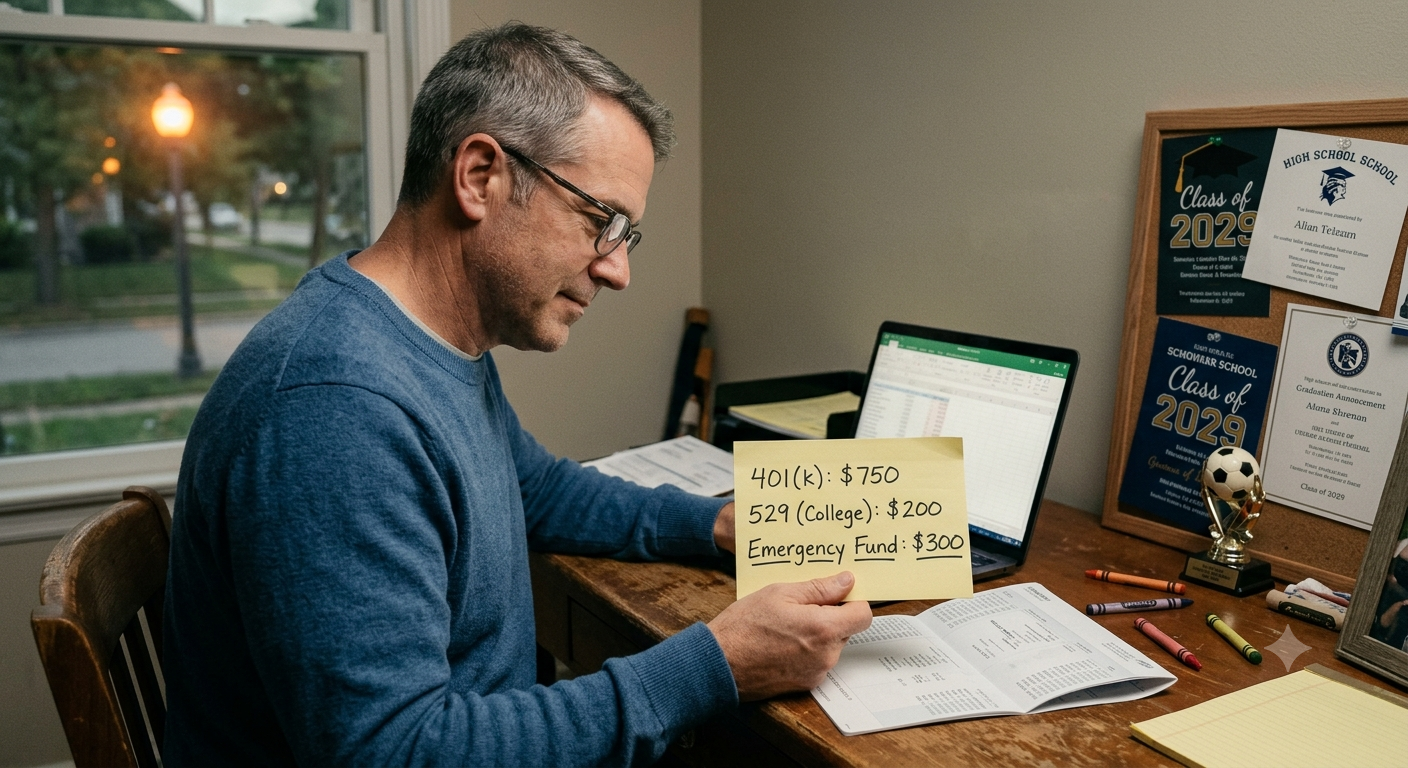
Open your accounts and write down three numbers: the exact monthly dollar amount going into retirement, into a liquid reserve, and into college. Three numbers on one page. If any of them is a zero, you have found a goal you turned into a sequence.
Maxing one goal while the others sit at zero is not discipline. It is a sequence nobody meant to choose. The families that get this right are not the ones with the most income or the most willpower. They are the ones who gave every goal a floor and let automation carry all of them at once, so the setback that arrives fast meets a plan that was already funded to meet it.