Some Money Only Moves on the Way Out
When I left a corporate finance career to start TAMMA, I forfeited equity I had earned and never put a number on it. I knew the shares were there. I knew leaving meant walking away from the unvested part. And I decided to go anyway, which was the right call, so I let the number stay vague, because looking at it directly would only have made a settled decision feel worse.
That is not the behavior of someone careless with money. I spent two decades being paid to think about exactly this kind of thing. It is the behavior of someone handling a financial decision under the worst possible conditions, which is what a job change is for almost everyone.
A job change is the single moment when the entire balance sheet has to be handled at once, on a deadline, by a person who is also managing an emotional decision, a new role, and a hundred logistical details that feel more urgent than they are. It is the worst setting for careful financial work. It is also exactly when the most irreversible financial work has to get done.
This is the last piece in a short series, and it follows directly from the one before it. That piece was about the difference between the skill that builds wealth and the skill that holds it. A job change is that switch, forced into a two-week window. Everything you accumulated by habit suddenly needs a structural decision, and the calendar does not care whether you are ready.
The Equity You Leave Behind
If your pay includes shares that vest over time, some portion is almost always unvested on any given day. When you leave, that portion generally stays behind. You never held it, so it never shows up as a loss anywhere. It is a cost that is completely invisible unless you deliberately go and look for it.
For a senior professional a few years into a grant schedule, the unvested piece can be substantial. None of that is a reason to stay in a job you should leave. A better role can be worth far more than what you forfeit. The point is narrower, and it is about sequence. The forfeited equity is part of the price of the move, and a price you have not calculated is a price you cannot weigh against what you are gaining. Know the number before the decision, not months after it, when it surfaces as a vague regret you cannot quite source.
The Payout You Cannot Reschedule
Deferred compensation is where a job change does real and permanent damage, because the damage is often locked in before you ever hand in notice.
If you have been deferring income into a plan, leaving usually triggers a payout, and the timing of that payout tends to be governed by elections you made years earlier under rules you cannot revisit now. Many plans pay the full balance out over a short window after departure. So income you deliberately spread across future years can land all at once, in a single tax year, stacked on top of what you earn at the next job. The thing you did to smooth your income can un-smooth it violently at the exit.
These plans vary too much for anyone to prescribe a right answer from an article, and I am not going to. Two facts are worth holding regardless of plan. The election rules are frequently irreversible, and the deferred balance is usually an unsecured promise from the employer rather than money set aside for you. Both of those mean the same thing in practice. If you have deferred comp, its payout timing belongs in the decision before you sign, because once you have left, most of the choices about it are already behind you.
The Rollover That Feels Like an Errand
Everyone knows the 401(k) has to go somewhere. The problem is never awareness. The problem is timing.
The rollover decision usually gets made in the first busy week at the new job, when it feels like an item to clear off a list rather than a choice that will shape a large account for the next two decades. So it gets done fast and thoughtlessly, or it gets left behind entirely, becoming one more orphaned account at a former employer that no one is watching or rebalancing.
Here is the part that removes the pressure. The rollover is not actually urgent. Nothing harmful happens if the account sits where it is for a few extra weeks while you make a considered decision about where it should live and how it should be invested. What is costly is letting a twenty-year decision get made at the speed of forwarding your mail, simply because it landed in the same pile.
The Cash That Makes the Difference
There is a fourth item, and it is the one that decides whether the first three are manageable or a crisis. Reachable cash.
If you leave without the next role fully locked, or if any gap opens between the last paycheck and the first new one, the only question that matters in the moment is how many months you can cover from money you can actually get to. Not money inside a retirement account, where reaching it creates a tax event on top of everything else. Money you already paid tax on, sitting somewhere you can spend it.
This is the direct descendant of the exercise from the last piece. The households that move through a job change without strain are almost always the ones whose reachable cash was sized to the life they actually have now, not to the life they had when they first set an emergency fund a decade and two raises ago. A job transition is precisely the event that fund exists for, and it is precisely the event during which people discover it was never resized.
One Page, Four Things
So here is what to do, and the timing matters as much as the content. Do this before you are anywhere near a decision, so that when a window opens, whether you chose it or not, the thinking is already done and only the paperwork is on a clock.
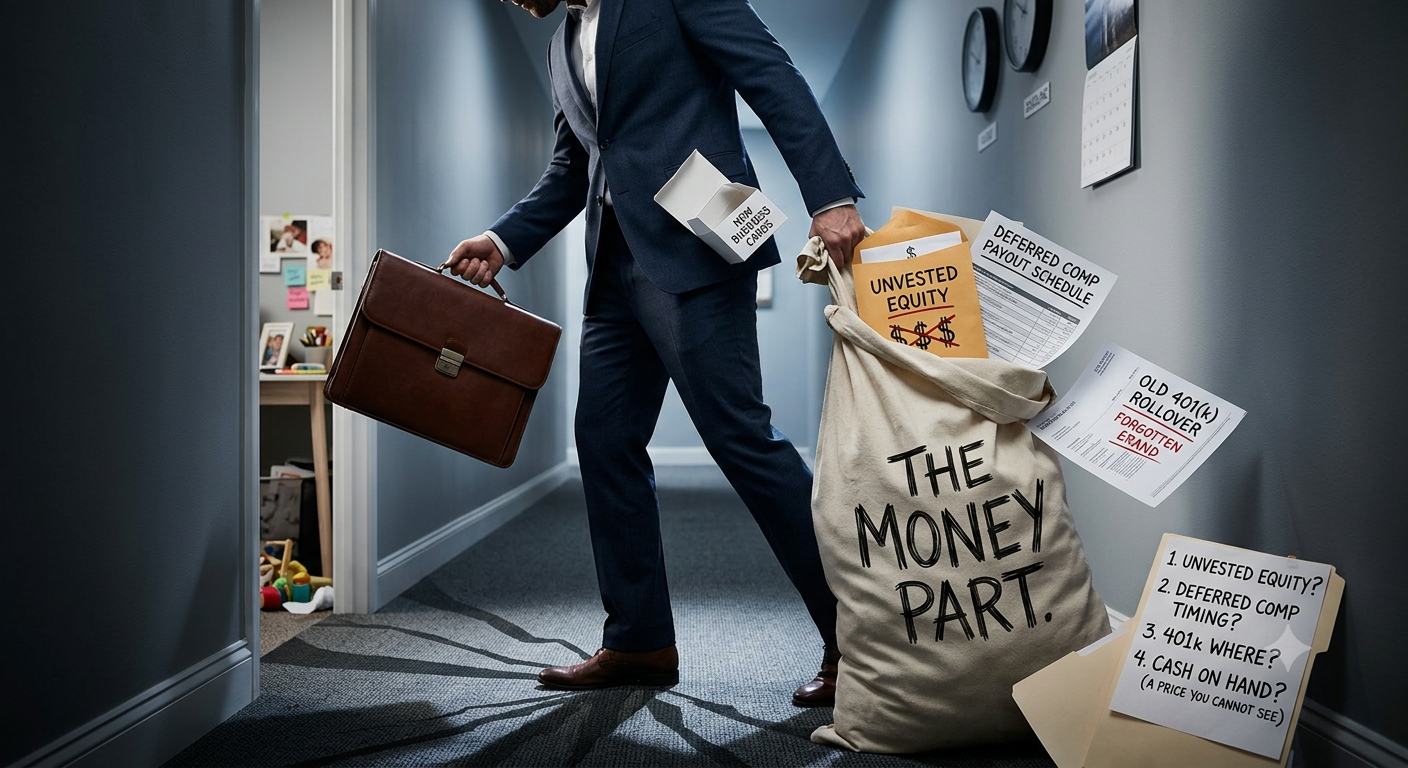
Put four things on one page. First, your unvested equity and the dates it would vest, so you can see what leaving this year would cost. Second, any deferred comp and its payout schedule, so a lump you cannot reschedule does not surprise you. Third, your current 401(k) balance with a calm note on where it would go, decided in advance rather than in the first hectic week. Fourth, the number of months you could cover from cash outside a retirement account.
You are not deciding to leave. You are making sure that the day the question arrives, the money decisions are already thought through, and the deadline applies only to the forms. That is the whole difference between handling a transition and being handled by one.
Morgan Housel wrote that getting rich and staying rich are different things that require different skills. Across the past few weeks, that line has done a lot of work, and this is where it comes to rest. The habit that builds a career of savings is one skill. Handling the day that career changes hands is another one entirely, and it arrives on a clock. The page will not decide for you. It just means that when the window opens, you meet it with the second skill already in hand, instead of discovering on the worst possible week that you only ever practiced the first.